Brine, Heat and the Bankability Test: UK Geothermal Lithium in 2026
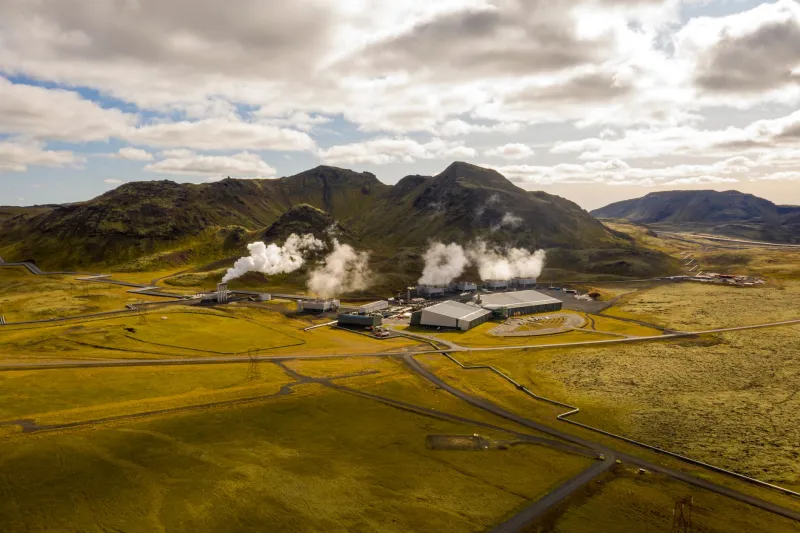
Geothermal lithium is usually presented in the UK as a two-revenue story: heat for district networks and lithium for batteries. For business readers, the more useful question is not whether the chemistry can be made to work in a laboratory. It is whether a project can survive the sequence of de-risking events that lenders, offtakers, insurers and regulators will impose before capital is released.
That sequence is now becoming visible. The Cornish geothermal cluster has moved from exploration rhetoric to pilot-scale processing and heat offtake discussions. Several consortia are testing direct lithium extraction, or DLE, on brines produced alongside heat. Yet the gap between a successful pilot and a bankable supply chain remains wide. In 2026, geothermal lithium should be judged less as a resource story and more as an integrated process, permitting and contract story.
The Diligence Question Is Not the Resource
A lithium concentration in parts per million is not a reserve. For brines, the relevant variables are flow rate, pressure, temperature, reinjection performance and uptime. A project can hold attractive lithium grades and still fail if the aquifer cannot sustain commercial flow without pressure decline or if reinjection risks clogging the formation.
The UK’s Cornish brines are generally lower in concentration than the salars of South America or some North American sedimentary basins. That makes DLE selectivity and operating cost more important, not less. The commercial case depends on processing large volumes of brine efficiently and returning the spent brine underground in a way that satisfies the Environment Agency and the local minerals planning authority.
Before a project can be underwritten, it needs a continuous operating record, not a series of batch tests. A pilot that runs for weeks at representative flow rates, with published recovery rates and reagent consumption, is more useful than an isolated lithium result. The market should ask for mass balances, water balances and parasitic power figures. Without them, the resource statement is incomplete.
Direct Extraction Must Be Judged as a Process Plant
DLE is often described as a simple filter for lithium. In practice it is a chemical plant with upstream and downstream dependencies. Selectivity against sodium, potassium, magnesium and calcium matters. Reagent supply, regeneration cycles, membrane life and waste streams all affect operating cost. The process also needs to be tolerant of variable brine chemistry, because geothermal systems rarely deliver a perfectly stable feedstock.
For UK projects, the energy penalty deserves particular scrutiny. Pumping, heating, DLE and conversion all consume power. If a project is co-located with a heat network, some of that energy may be available at a discount, but it is not free. The bankable case should show a clear split between heat revenue, lithium revenue and the cost of the power and chemicals used to produce both.
A further test is conversion. Lithium chloride or lithium carbonate from a UK brine must be qualified for battery supply, which usually means a downstream conversion route and a customer willing to test the product. A project that stops at a mixed salt or an intermediate concentrate has not yet proved a saleable supply chain.
Heat Revenue Is an Anchor, Not a Subsidy
Heat offtake is the quiet advantage of geothermal lithium. A district heating network, a greenhouse operator or an industrial user can provide baseload revenue that hard-rock lithium projects rarely enjoy. That anchor can help underwrite drilling and surface facilities, and it improves the project’s social and planning case by linking it to local energy needs.
But heat is not a blank cheque. UK heat networks are often developed by local authorities or community interest companies with limited balance sheets. Tariffs can be regulated or politically sensitive. The heat customer must be creditworthy, and the network must be built. A letter of intent is not the same as a signed heat supply agreement with a volume commitment and a pass-through mechanism for operating costs.
The strongest projects will be those where the heat customer is also a strategic partner, not merely a buyer. Co-development of the subsurface, surface plant and network can reduce duplicated permitting and shared infrastructure costs. It can also make the lithium plant easier to finance, because the heat revenue covers a larger share of fixed costs during ramp-up.
Permitting and Mineral Title Set the Timetable
UK geothermal lithium projects sit at the intersection of water abstraction, environmental permitting, planning and mineral rights. Each can move at a different pace. The Environment Agency will focus on abstraction, discharge and reinjection. The minerals planning authority will consider surface development, traffic and restoration. The Crown Estate or other landowners may control access to deeper formations.
These are not administrative details. They determine the critical path. A project that has a promising DLE pilot but no agreed reinjection strategy is not near construction. A project that has not settled mineral title may find that the value of its lithium stream is contested. Diligence should map every consent, land interest and ownership right before assigning value to the resource.
Offtake Credibility Is the Final Filter
Battery supply chains are conservative. Cathode and cell manufacturers qualify feedstock slowly, and they rarely sign binding contracts with unproven producers. For UK geothermal lithium, the credible route is likely to involve a conversion partner and a customer with a European or UK footprint. A non-binding memorandum of understanding is a useful signal, but it is not offtake.
The diligence test is whether the customer has agreed to volume, specification, price mechanism and ramp-up schedule. It also matters whether the product can meet the carbon intensity and traceability requirements that European buyers increasingly demand. Geothermal lithium may have a strong sustainability narrative, but the buyer will want auditable data, not a slogan.
How It Compares With Hard Rock
Hard-rock lithium projects in the UK and Europe face their own risks: mining permits, waste management, community opposition and energy costs. Their mineralogy is often better understood, and their processing routes are more established. Geothermal brine projects avoid the open pit and tailings footprint, but they carry subsurface and process risk that is harder to standardise.
The comparison should therefore be made on a risk-adjusted basis. A hard-rock project with a defined orebody and a conventional concentrator may be easier to finance, even if its permitting timetable is long. A geothermal project with a strong heat anchor and a proven DLE process may offer lower surface impact and diversified revenue, but only if the subsurface and permitting risks are genuinely retired.
The Tests That Matter in 2026
For UK geothermal lithium to justify capital this year, five tests should be met. First, continuous pilot operation at representative flow rates, with transparent mass and water balances. Second, a reinjection and pressure management plan accepted by the regulator. Third, a creditworthy heat offtake that covers a material share of fixed costs. Fourth, a downstream conversion and qualification route with a named customer. Fifth, a clear mineral title and land access position.
No single UK project may satisfy all five today. The Cornish cluster is closest on subsurface data and public visibility, but it still needs to prove sustained process performance and commercial offtake. Other sedimentary basins may offer larger heat opportunities, yet they are earlier in characterisation.
The commercial test for geothermal lithium is therefore not whether the UK can produce lithium from brine. It is whether a project can assemble the subsurface, process, heat, permit and offtake evidence into a financeable package. Until that package exists, geothermal lithium remains a promising option rather than a bankable supply source.