The Quay Behind the Quarry: Diligencing Port Capacity in UK Mineral Supply
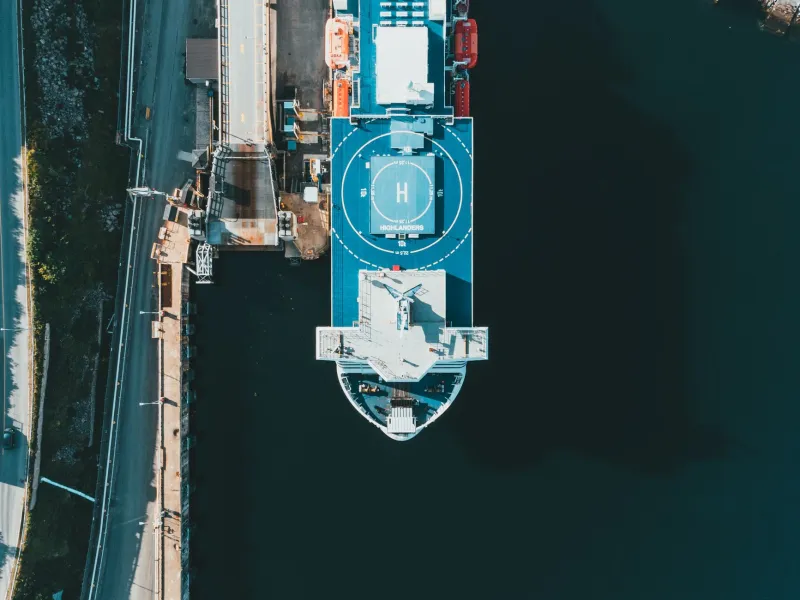
A quarry is only as valuable as the route that carries its product to market. For a growing share of UK mineral supply, that route runs across a wharf before it runs across a weighbridge. Cement clinker, specialist aggregates, marine-dredged sand and gravel, and an expanding list of processed critical minerals all depend on port capacity that is frequently older, more constrained and more contested than the reserves they serve.
Yet in many transactions, the wharf appears as a single line in a logistics appendix. Berth availability is assumed, storage is estimated, and dredging is treated as an operational detail rather than a property right. That asymmetry is becoming harder to defend. In 2026, with UK industrial policy leaning on domestic supply chains and import resilience, port capacity is a strategic filter for mineral investors rather than a passive service.
Why the wharf deserves a diligence file
The UK is not short of coastline. It is short of berths that can accept the right vessel, at the right tide, with the right storage behind them and the right consents in front of them. Many general cargo wharves sit within port estates whose masterplans now favour higher-value uses, offshore energy fabrication or container traffic. Others face maintenance backlogs on lock gates, quay walls and dredged channels. A berth that operated comfortably a decade ago may now be constrained by vessel size, cargo segregation requirements or environmental limits on dust and runoff.
For a minerals business, those constraints transmit directly to revenue. A reserve estimate assumes a saleable tonnage; a wharf determines whether that tonnage can reach the customer at a competitive freight cost. If the berth can only take part-laden vessels, or if storage is insufficient to build a full cargo, the effective capacity of the mine or processing plant is lower than the technical capacity on paper. Investors should therefore treat wharf access as a gating item, not a post-completion optimisation.
Test one: berth geometry and availability
The first question is physical. What length, beam and draft can the berth accept, and across how many hours of the tide? A berth that handles 5,000-tonne coasters is not interchangeable with one that handles 25,000-tonne handysize vessels. The difference affects freight economics, supply frequency and the working capital tied up in stockpiles.
Availability matters as much as geometry. A berth shared with other users may be booked through a port authority or terminal operator, and priority may sit with long-standing customers. Diligence should ask for actual berthing records, not indicative schedules. It should also establish who controls the berth, on what tenure, and whether the mineral business has enforceable rights or merely a reasonable expectation of access. Exclusivity, minimum throughput commitments and tariff escalation clauses all belong in the investment paper.
Test two: storage and cargo segregation
Mineral cargoes are not interchangeable. Cementitious materials are sensitive to moisture. Aggregates require segregation by size and specification. Critical-mineral concentrates and processed salts may need covered storage, drainage controls and dust management. A wharf with ample open yard space may still be unsuitable if it cannot keep cargo dry, separate and identifiable.
Storage capacity also sets the rhythm of trade. If the terminal can hold only one vessel parcel, the business cannot take advantage of favourable freight rates or build stock ahead of seasonal demand. Diligence should compare storage capacity with expected cargo size, turnaround time and peak inventory. The right metric is not total yard area but usable, consented, segregated capacity under normal weather conditions.
Test three: dredging rights and seabed consents
Access to water is not the same as access to depth. Many UK berths depend on maintenance dredging to keep their approach channels and berth pockets usable. The right to dredge, the right to dispose of dredged material and the obligation to pay for both are frequently split between the port authority, the landowner, the Environment Agency, the Marine Management Organisation and, in some cases, the Crown Estate.
A minerals investor should establish who holds the dredging consent, when it expires, what conditions attach to disposal and how maintenance costs are allocated. A berth that looks cheap on paper may carry an uncapped dredging liability or a consent that is vulnerable to review. In a tighter environmental permitting environment, the ability to maintain depth can be as decisive as the ability to maintain planning consent on land.
Test four: landside links and the last mile
Port capacity is not only a marine matter. The wharf must be connected to the market by rail, road or both. Rail sidings, loading gauges, bridge weights and yard shunting capacity determine whether bulk mineral cargo can move economically to inland processors and construction sites. Road access raises its own issues: HGV routing, curfews, air quality and the willingness of local authorities to accept additional movements.
For critical minerals, the landside question may be about specialised handling and secure storage rather than bulk conveyance. For aggregates and cement, it is about sustained heavy-goods movement. In either case, the diligence should map the actual route from berth to customer, including any third-party infrastructure that could become a bottleneck or a point of commercial leverage.
Test five: consents, neighbours and the port masterplan
A wharf operates within a stack of consents: harbour powers, planning permission, environmental permits, noise and dust controls, and sometimes hazardous-substance rules. These should be read together rather than accepted as a bundle. A terminal may have permission to store minerals but not to process them; it may be able to import but not to export; it may face operating-hour limits that conflict with tide windows.
The wider port estate matters too. Neighbouring uses can change. A port masterplan that shifts towards offshore wind, cruise or residential mixed-use may leave general cargo wharves stranded or revalued. Investors should ask how the mineral use fits the port authority’s long-term strategy and whether the tenure extends beyond the next masterplan review.
Bringing the wharf into the valuation
The practical conclusion is that wharf capacity should be modelled explicitly. Throughput should be capped by berth availability, storage and landside evacuation, not by the nameplate capacity of the quarry or plant. Freight assumptions should be tested against realistic vessel sizes and tide windows. Maintenance obligations, tariff reviews and lease renewals should be visible in the cash-flow model rather than buried in the notes.
None of this argues that UK mineral projects are uniquely exposed. It argues that port access is now a differentiator. Two sites with comparable geology and permits can have very different commercial futures if one controls a viable berth and the other depends on a shared, shallow or contested wharf. In a market where supply chains are being reassessed for resilience, the quay behind the quarry is part of the resource story.
For investment committees, the test is straightforward. Ask for the berth booking record, the storage plan, the dredging consent and the landside route. If those documents are unavailable or inconsistent, the logistic assumption is not an assumption at all. It is an unhedged risk.