Two Ledgers, One Wood: Auditing Carbon and Habitat Income Before the Term Sheet
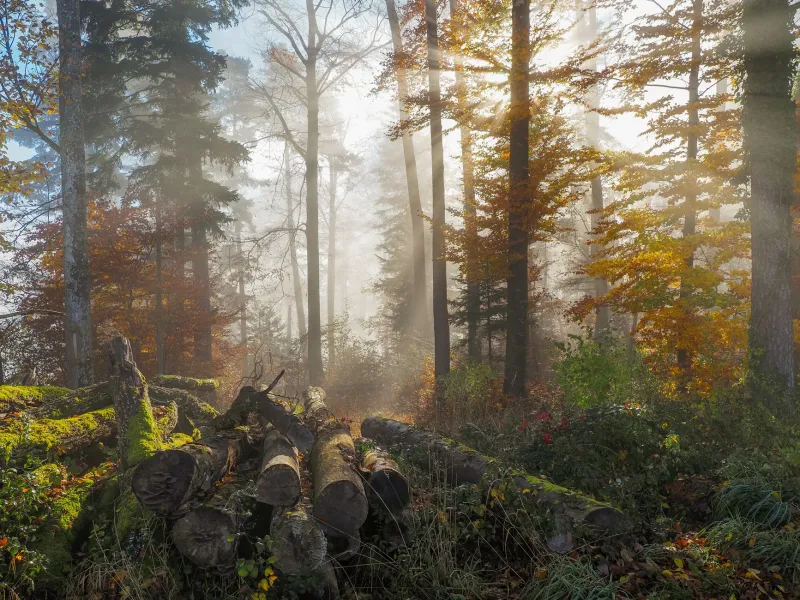
A generation ago a UK woodland valuation was a timber exercise with a land-value floor. A chartered forester walked the compartments, assigned yield classes, netted off harvesting costs and applied a discount rate. Carbon was a footnote, and biodiversity was a constraint on operations rather than a line of income.
That has changed. A seller bringing a 300-hectare estate to market in 2026 is now likely to present a schedule of standing timber, a registry extract of pending carbon units, and a habitat plan referencing biodiversity net gain. Three income streams, one title. The difficulty for a board approving the acquisition — or a credit committee underwriting it — is that only the first of those streams is liquid, contracted and priced against a traded market.
Why the pricing has shifted
Three policy currents have converged. England's tree-planting targets remain some distance from the trajectory implied by the statutory 16.5 per cent woodland cover ambition for 2050, and every administration since 2019 has looked to private capital to close the gap. The Woodland Carbon Code has matured into a functioning registry with validation, verification and unit serialisation. And mandatory biodiversity net gain in England, commenced in stages from February 2024, has created a second environmental commodity with a legal trigger behind it.
At the same time the timber case has strengthened. The UK remains one of the world's largest net importers of forest products, and the policy push toward greater use of home-grown timber in construction has made domestic supply a strategic question rather than a purely commercial one.
The consequence is that woodland is now marketed as an infrastructure asset with environmental attributes. That framing is defensible. But the diligence discipline it requires is closer to project finance than to estate agency.
The three streams, and how each is evidenced
Standing timber. This is the mature part of the ledger. Sawlog, small roundwood and biomass are traded, and a competent valuation discounts a felling programme against known costs, haulage distances and mill demand. The uncertainties — species mix, access, yield class, windthrow exposure — are well understood and routinely priced.
Woodland carbon units. Under the Woodland Carbon Code, a validated scheme generates Pending Issuance Units, which convert to Woodland Carbon Units only after verification confirms the sequestration has actually occurred. The distinction matters enormously to a buyer. A PIU is a forward claim on future tonnes; a WCU is a verified tonne. The former carries delivery risk, the latter carries a permanence obligation measured over 30 or 100 years and supported by a buffer contribution held against failure.
Biodiversity units. Off-site habitat creation can generate units saleable to developers seeking to meet the 10 per cent net gain requirement, secured through planning obligation or conservation covenant and registered with the local planning authority. Statutory credits, priced by Defra deliberately above the market to operate as a last resort, set something of a ceiling.
Where projections detach from delivery
The recurring failure in investment papers is to run all three streams through a single discounted cash flow at a single discount rate. They are not comparable assets. Carbon is voluntary-demand, reputationally exposed and excluded from the UK Emissions Trading Scheme, meaning no compliance buyer of last resort exists. Biodiversity units are local, illiquid and dependent on a planning system whose demand is cyclical.
Four specific tests separate the deliverable from the aspirational.
Additionality. Carbon and habitat income both depend on demonstrating that the land use would not have happened anyway, and that no other scheme has already claimed the same activity. Where planting was grant-funded, the interaction between grant conditions, the Woodland Carbon Guarantee where a project is enrolled, and the sale of units needs to be traced line by line. Double-funding is the fastest route to a restated asset.
Permanence and buffer. The buffer contribution is not the buyer's asset — it is the insurance premium against it. A model that treats 100 per cent of gross sequestration as bankable is overstating the collateral by a margin set by the permanence period chosen.
Verification timing. Early verifications are front-loaded, then spaced out. A buyer acquiring a 2024 planting in 2026 is buying PIUs most of which will not convert for years, against a counterparty — potentially the seller's retained entity — whose covenant weakens with time.
Biological and climatic reality. Yield class assumptions for Sitka spruce on upland sites are increasingly stress-tested against drought, windthrow, and pests. Ips typographus in the south-east, Phytophthora ramorum in larch, ash dieback, and grazing pressure from deer and grey squirrels all degrade the timber case, and can degrade the carbon case with it if mortality triggers a buffer deduction.
The questions a lender should put in writing
- Who owns the carbon rights, and are they severed from the freehold, the timber rights, or any tenancy or sporting lease?
- Is the project validated, and by whom? Is the registry account in the borrower's name and free of encumbrance?
- What is the permanence period, the buffer deduction, and the mechanism for replacing units if the scheme underperforms?
- Which grant agreements attach to the land, and what clawback or consent provisions bind a change of control?
- Is the site clear of ancient woodland designation, tree preservation orders and statutory nature conservation designations that would constrain harvesting or habitat management?
- For biodiversity units, is there an executed planning obligation or covenant, a registered gain site, and an identified purchasing authority?
- Does the felling programme hold the licences it needs, and does the management plan comply with the UK Forestry Standard and forestry EIA thresholds?
Structuring around uncertainty
The market practice emerging among UK lenders is to lend against the timber and land value at conventional loan-to-value, and to treat environmental units as an equity cushion rather than as security. Where carbon income is material to the business plan, it is increasingly modelled with a delivery haircut, a longer-dated revenue start, and a covenant tested on verified units rather than contracted ones.
Buyers, meanwhile, should be explicit about which business they are acquiring. A working forest with a carbon overlay is a resource business with an environmental dividend. A recently planted scheme whose cash flows depend principally on unit sales is a carbon story with trees attached — and it deserves the underwriting scrutiny, the counterparty analysis and the sensitivity testing that any early-stage environmental project would attract.
Both can be good assets. They are not the same asset, and the price paid for one should never be justified by the arithmetic of the other.